For UK 9-to-5ers who earn decent money and still run short before payday
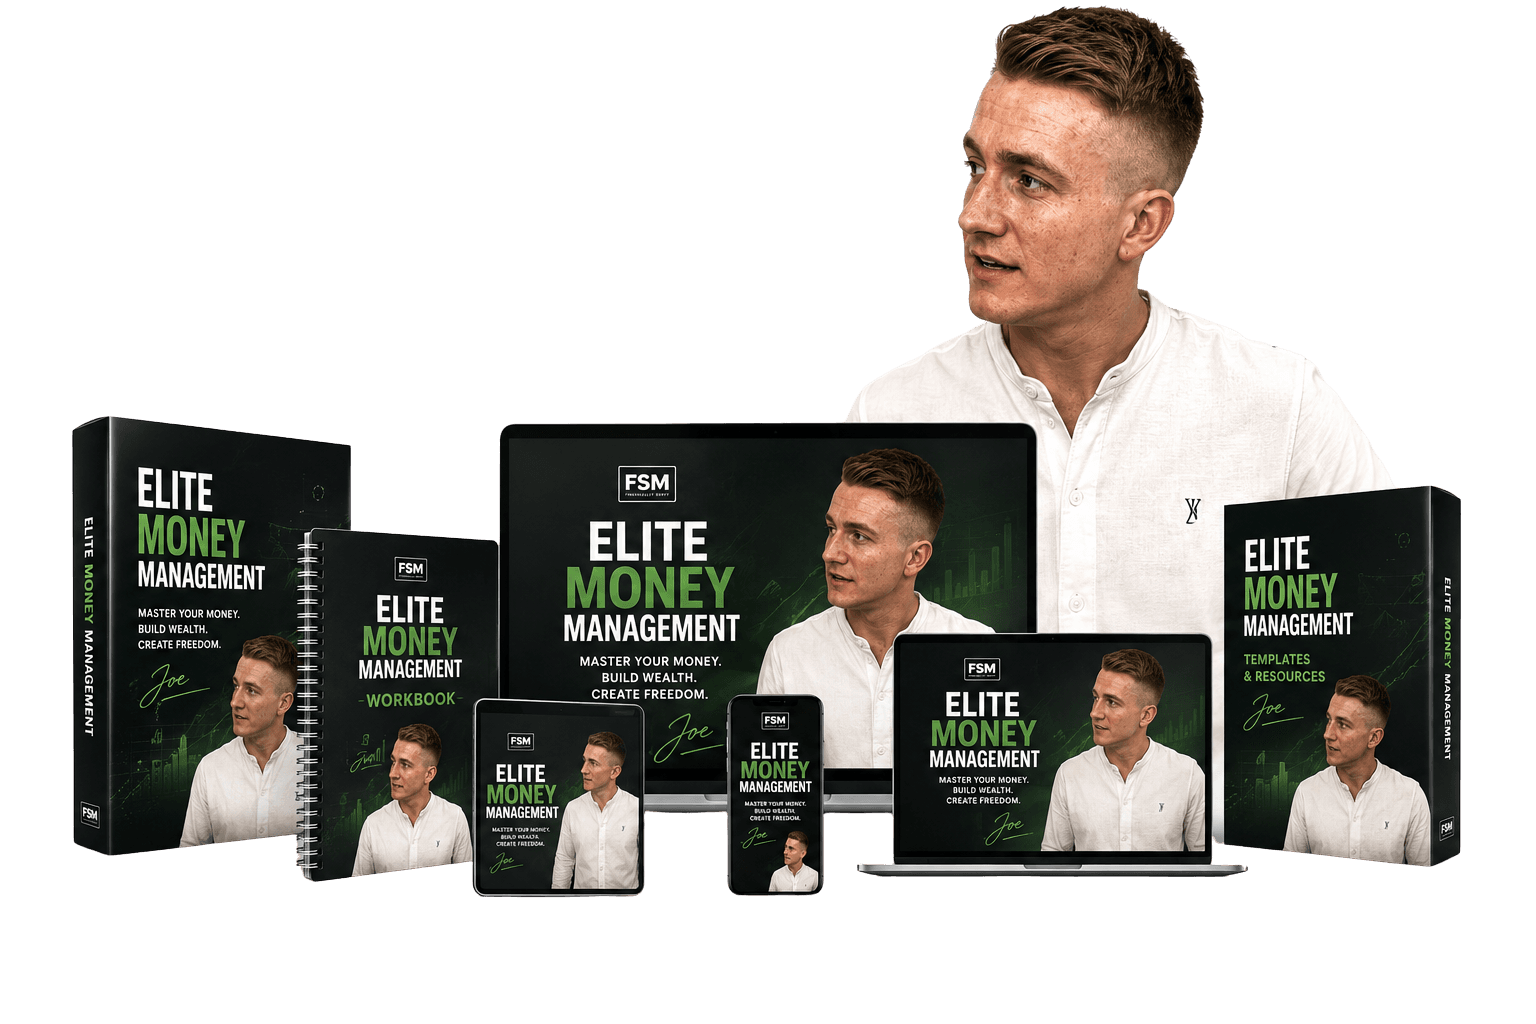
Let me show you the money system 2,138+ people have used to get on top of their money and save an extra £518–£5,953 a month
It's the spreadsheet and process I use with my own money. You set it up once, and from then on every pound you earn has a job before the month even starts.
Joe, founder of Financially Savvy.
Went from −£40k to a £1M+ net worth using this exact system.
Elite Money Management System
Instant access · one-off payment
Step 1 of 2. Where should we send it?
Covered by a 365-day money-back guarantee.
“It got to July and I was thinking, what is this magic? Where is all this money coming from? And obviously I'd had it the whole time. I just didn't have a clue what I was doing with it.”
Joe, founder of Financially Savvy
From Joe
A quick word before you decide
Most people think the fix is earning more. It isn't.
I've watched people double their salary and still finish the month with nothing, because more money without a plan just turns into a bigger lifestyle.
What changes things is a plan for the money you already have. That's all this is. A simple way to give every pound a job before the month starts, so you stop guessing and start getting ahead.
It's helped a lot of people get off the payday-to-payday treadmill and finally feel calm about money. If you actually use it, I'm confident it'll do the same for you. And if it doesn't, you've got a full year to ask for your money back.
Joe
Founder, Financially Savvy
What you get
Everything that comes with it
Instant access as soon as you've paid. Nothing is posted and there's nothing to wait for.
- 01
The money system
The process I used to go from −£40k to a £1M+ net worth. It's how I decide where every pound goes, written down so you can copy it.
- 02
The spreadsheet
Put in your income and your bills and it does the maths. You'll see exactly what you can save, invest and spend each month.
- 03
The setup walkthrough
Follow along step by step and have it running today, even if you've never kept a budget going for longer than a fortnight.
- 04
The 'stay consistent' plan
Most people give up on budgeting around week two. This is the part that stops that happening.
- 05
The lifestyle-inflation fix
How to save more every time your pay goes up, without cutting out the things you actually enjoy.
- 06
Bonus: expense tracking + the autopilot guide
So surprise bills stop knocking you sideways, and the good habits keep going without you having to think about them.
Results
What members say it changed
Taken from filmed interviews and messages members sent us. First names only, because it's their money.
| Member | Where they are now | Result |
|---|---|---|
| NaomiRetiring at 53 instead of 67 | Retiring at 53 instead of 67 | £2,500 a month freed up |
| JordanEarly 30s, retiring at 50 | Early 30s, retiring at 50 | Around £2,000 a month freed up |
| CarrieSingle mum, one income | Single mum, one income | £1,300 a month freed up |
| TammyRetiring at 57 | Retiring at 57 | From −£500 to +£1,000 a month |
| CarlA&E doctor, retiring at 50 | A&E doctor, retiring at 50 | £900 a month freed up |
| MattStarted at 27, retiring at 47 | Started at 27, retiring at 47 | Now investing £500 a month |
| Lucy & DaveRang round every bill | Rang round every bill | Around £400 a month saved |
Individual results. Not typical and not guaranteed. They depend on your income and how much you put in.
“When we found you on Instagram we were like, are we mental? This is a guy off Instagram, are we just going to get conned? And I'm so pleased that I did it, because we didn't get conned.”
“I used to be waiting for payday every single month. I'd get to week three and have to make £50 stretch for the next 10 days. Now my only focus is how I can earn more, rather than needing more just to get by.”
“I just made my final credit card payment. Actually 2 months early. We've got an emergency fund, did Christmas with no credit cards, our holiday's booked and paid from our sinking funds, and our investments are automated. What am I really saying? The system works. Can't thank Joe enough.”
“Is there a value on reassurance? I used to fixate on numbers going to bed. Physical nightmares. I don't have them anymore. The financial fear has totally been eliminated.”
“I've still been able to live life. It's not like everyone's down the pub and I'm at my limit so I'm not going. I've been able to still live life and save, and budget a lot easier.”
Hear it from them
Watch 4 moreShow fewer
Why not just download a budgeting app?
Fair question. Most apps show you what you spent last month. That's useful, but by the time you see it, the money's already gone.
This works the other way round. On payday, every pound gets a job: bills, savings, investing, and money you're allowed to spend without feeling guilty about it. You decide once, then mostly leave it alone.
That's also why people stick with it. It doesn't rely on you being disciplined every single day.
365day guarantee
Use it for a whole year
If, after a year, it hasn't made a real difference to how you handle your money, email us and we'll refund every penny. You don't need to explain yourself.
Questions people ask before buying
Who is this for?+
Anyone with a steady income who still feels like their money disappears each month, whether you're on £25k or £150k. If you want a clear plan for the money you already make, it's for you.
I've tried budgeting apps and spreadsheets before. Why is this different?+
Apps track what already happened. This tells your money where to go before you spend it, and it comes with a plan for staying consistent, which is the bit most people are missing.
Do I need to be good with spreadsheets?+
No. You type in your numbers and follow the setup walkthrough. If you can fill in a form, you can do this.
How quickly will I notice a difference?+
You can have it set up the same day. Most people feel clearer straight away and see real money freed up within their first full month.
Is it a subscription?+
No. It's a one-off payment and you keep it.
Is this financial advice?+
No. It's education. It shows you how to organise your own money. It doesn't tell you what to buy or sell.
Right, that's everything.
It's £47 while launch pricing lasts, then it goes back to £97. You get it straight away, it's yours to keep, and you've got a year to decide whether it was worth it.
If you've read this far, I think you already know whether it's for you.
Joe
Founder, Financially Savvy
Elite Money Management System
Instant access · one-off payment
Step 1 of 2. Where should we send it?